
You could be in pain, missing work, and staring at medical bills that feel unreal. People around you keep offering “advice” about what you should do after your accident, and every piece of it seems to conflict with the last one. You are tired, worried about money, and afraid that one wrong move will ruin your chance to be treated fairly, so you consider talking to a personal injury lawyer.
The hardest part is not just the injury. It is the confusion. You hear stories about people getting “huge settlements” for minor accidents, then you are told your case is probably not worth anything. You are told to “just trust the insurance company,” while the same company calls you nonstop, asking for recorded statements and pressuring you to “wrap this up.”
The core problem is simple. Certain personal injury myths quietly push you to make choices that help insurers, not you. When you believe those myths, you can lose thousands of dollars, sometimes your entire claim. Here is the short version. Do not rely on what you have “heard” from friends, adjusters, or social media. Learn the truth about these personal injury myths that could cost you money before you sign anything, post anything, or say anything official.
Common personal injury myths that quietly drain your settlement
One of the most damaging myths is that the insurance company is “on your side.” The adjuster may sound kind and patient. They may tell you they “just need a few details” to process your claim. Their job is to limit what the company pays out. That means finding reasons to blame you, question your injuries, or argue that your treatment was unnecessary.
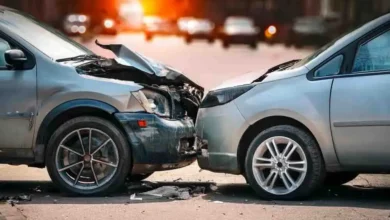
Imagine you are rear-ended at a stoplight. Your neck feels sore, but you assume it will pass. The adjuster calls the next day, sounds sympathetic, and asks to record your statement “so we can move things along.” You say you are “fine, just a little sore” and that maybe you “stopped a bit fast.” Weeks later, your pain is worse, you are sent for imaging, and a doctor finds a real spine injury. The insurer points back to your own words and uses them to argue that you were not hurt or were partly at fault. A few casual phrases can cut your claim value in half.
Another stubborn myth is that minor aches and pains do not justify a claim. People tell themselves they do not want to be “dramatic” or “one of those people.” So they skip the doctor, keep working, and hope it fades. Soft tissue injuries, concussions, and back problems often start small then grow into chronic conditions. If you wait too long to get medical care, the insurer will argue the injury came from something else, not the accident.
There is also pressure to trust that all insurance is basically the same and always legitimate. Many people do not realize that some offers, especially around health coverage after an injury, can be scams. Scammers target people who are scared and looking for quick help. Federal agencies share clear warnings on understanding legitimate insurance options, and ignoring those warnings can put you in a worse financial position just when you are most vulnerable.
How myths about personal injury claims create emotional and financial strain
These myths do not only hurt your legal rights. They wear you down emotionally. You may feel guilty even considering a claim, as if you are doing something wrong by asking to have your bills covered. That guilt benefits the other side. It keeps you quiet and compliant.
Take the myth that “a lawyer will just take all your money.” People repeat this so often that many injured people never even speak to a personal injury lawyer. They accept the first low offer they receive because it feels “clean” and simple. Months later, when more bills arrive or they cannot return to the same kind of work, they realize the settlement does not even cover what they have already paid out of pocket.
There is also the myth that if you are partly at fault you have no case. In many places, you can still recover money even if you made a mistake, as long as the other party also shared blame. When you assume you have no rights, you never ask questions. You never gather documents or keep records. Evidence disappears. Witnesses move. By the time you figure out you might have had a claim, it is too late.
Scams add another layer of damage. Some companies try to sell “special accident coverage” or fake health plans right after you are hurt. They promise fast approval and cheap premiums, then disappear when it is time to pay medical bills. The Federal Trade Commission explains common patterns in health insurance scams that target consumers, and those patterns often show up after car crashes or other serious injuries.
On top of that, the stress of dealing with confusing insurance rules can push you to sign whatever is put in front of you. You might think, “I just want this over with.” That urge for quick closure is exactly what some insurers count on. They know if you are tired and unrepresented, you are more likely to settle for far less than the law would allow.
Key comparisons that show how myths affect your outcome
The difference between believing common myths and treating your situation like a serious legal matter is not subtle. It often shows up in how you handle evidence, medical care, and communication with insurers.
| Believing the myth | Taking informed action | Likely impact on your compensation |
| You give a casual recorded statement to the adjuster within 24 hours, minimizing pain. | You wait, get checked by a doctor first, and provide only basic facts in writing. | Recorded words are used to argue you are “not really hurt,” reducing or denying payment. |
| You assume soreness is “no big deal” and skip medical treatment for weeks. | You see a doctor quickly, follow orders, and keep all records and receipts. | Gaps in care let insurers claim your injury came from another cause, cutting your claim. |
| You think hiring a lawyer costs too much, so you handle negotiations alone. | You consult a personal injury attorney who works on a contingency fee. | Unrepresented claimants often accept low offers. Represented claims tend to resolve higher. |
| You buy “quick fix” health coverage from an unknown caller after your accident. | You verify any plan through trusted resources like government fraud alerts. | Scam plans leave you paying bills yourself, while scammers keep your premiums and data. |
| You assume partial fault means no claim, so you never gather photos or witness info. | You document the scene, keep contact information, and explore your legal options. | Lack of evidence weakens your bargaining power and future legal case. |
Government resources can help you separate real coverage from scams. The Office of Inspector General issues clear consumer alerts about health insurance marketplace fraud, which are especially relevant if someone contacts you about “special accident coverage” after you are hurt.
Immediate steps to protect yourself from costly personal injury myths
1. Get medical care and create a clear record
See a doctor as soon as you can, even if your pain feels manageable. Tell the provider exactly what happened and where it hurts, without exaggeration or minimizing. Follow the treatment plan. Keep copies of every bill, prescription, and work note. Accurate medical records are the backbone of any injury claim. Without them, you are relying on memory and hope, which insurers do not accept as proof.
2. Control what you say and what you sign
When the insurance company calls, be polite but brief. Confirm basic facts like the date, time, and location of the incident. Decline recorded statements until you fully understand your rights. Do not guess about your injuries or long term impact. Never sign medical releases, settlement agreements, or broad authorizations without reading them carefully and, ideally, having a professional review them. Once you sign a settlement, your case is usually over, even if your condition gets worse.
3. Talk with a qualified personal injury professional early
A short conversation with a personal injury lawyer can correct dangerous myths before they turn into expensive mistakes. Many work on a contingency fee, which means they are paid only if you recover money. Ask direct questions about their fees, how they communicate, and what they see as the strengths and weaknesses of your case. Use that information to decide how to move forward, even if you are not ready to make any big decisions yet.
Protecting your future by rejecting costly myths
You did not ask to be injured, and you are not greedy for wanting your medical bills, lost wages, and pain to be taken seriously. The stories that tell you otherwise are myths that benefit insurers and scammers, not you. When you replace those myths with clear information, you protect both your wallet and your peace of mind.
You have more control than it feels like you do right now. Get checked out. Keep records. Be careful with what you say. Reach out to a trusted personal injury lawyer or legal aid resource if you feel lost. Your claim, your health, and your future are worth more than quick guesses and half-true advice from people who do not have to live with the outcome.